2026 Student Loan Repayment Plans: New Federal Programs
Advertisers
New federal student loan repayment plans in 2026 introduce a pivotal 2.5% interest rate cap, aiming to provide significant financial relief to borrowers across the United States.
Advertisers
As we approach 2026, the landscape of student loan repayment is undergoing a transformative shift. New federal programs are set to introduce innovative solutions, most notably a 2026 Student Loan Repayment Plans: New Federal Programs Offering 2.5% Interest Rate Caps, designed to alleviate the financial strain on millions of borrowers. This development promises to reshape how graduates manage their educational debt, offering unprecedented stability and predictability.
Understanding the New Federal Programs for Student Loans
The federal government is rolling out comprehensive changes to student loan repayment, reflecting a commitment to making higher education more accessible and affordable. These new programs are not merely minor adjustments but represent a significant overhaul of existing structures, focusing on borrower protection and long-term financial health. The core of these reforms centers around simplifying repayment processes and introducing mechanisms to prevent crippling debt.
Advertisers
Historically, student loan interest rates have been a major point of contention, often leading to ballooning balances that make repayment seem insurmountable. The new federal programs address this directly by implementing an interest rate cap, a move anticipated to bring substantial relief to a wide range of borrowers. This proactive approach aims to stabilize the economic outlook for recent graduates and those still navigating their repayment journey.
Key Objectives of the 2026 Reforms
- Financial Stability: To provide borrowers with predictable and manageable monthly payments.
- Debt Reduction: To prevent interest from accumulating endlessly, thereby reducing the total amount repaid.
- Accessibility: To ensure that the cost of higher education does not become an insurmountable barrier.
- Economic Growth: To free up disposable income for borrowers, stimulating broader economic activity.
These objectives underscore a broader vision for a more equitable and sustainable student loan system. By tackling the root causes of financial distress among borrowers, the government hopes to foster a generation that can invest in their futures without being perpetually burdened by educational debt. The implications of these changes are far-reaching, affecting not just individual finances but also national economic trends.
In essence, the new federal programs represent a paradigm shift, moving away from a system that often felt punitive towards one that is supportive and designed for success. Borrowers should familiarize themselves with these upcoming changes to leverage the full benefits available to them.
The 2.5% Interest Rate Cap Explained
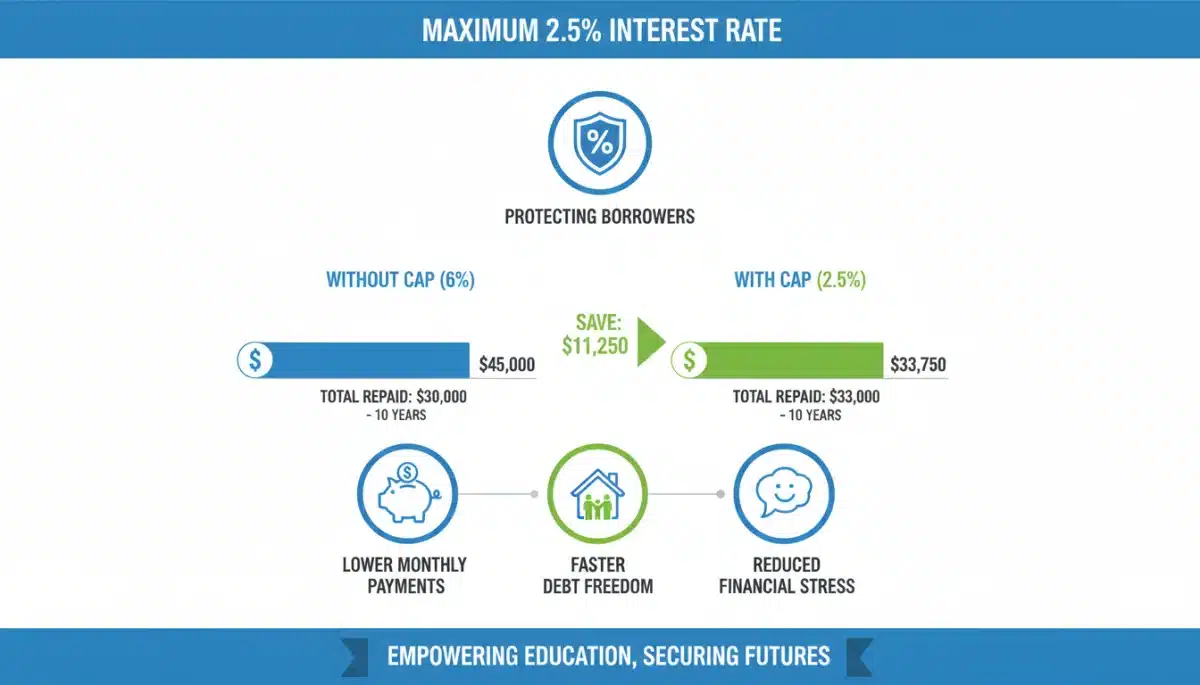
Perhaps the most impactful element of the 2026 student loan reforms is the introduction of a 2.5% interest rate cap. This cap is a game-changer for millions, setting a ceiling on how much interest can accrue on federal student loans. Understanding its mechanics is crucial for borrowers to grasp the potential savings and long-term financial benefits.
Currently, federal student loan interest rates can vary significantly, often adjusted annually based on market conditions. This variability can make financial planning challenging and lead to unexpected increases in repayment burdens. The 2.5% cap provides a much-needed safeguard, ensuring that interest rates do not exceed this threshold, regardless of prevailing market rates.
How the Interest Rate Cap Works
- Fixed Ceiling: All eligible federal student loans will have their interest rates capped at 2.5%.
- Automatic Adjustment: If a borrower’s original interest rate is higher than 2.5%, it will automatically be reduced to this cap.
- Protection Against Volatility: Borrowers are shielded from future interest rate hikes, providing long-term predictability.
- Applies to New and Existing Loans: The cap is expected to apply to both new loans originated in 2026 and existing federal student loans, though specific eligibility criteria will be detailed.
This cap is not merely a temporary measure; it is designed to be a fundamental component of the new repayment framework. It aims to prevent the common scenario where borrowers make consistent payments, yet their principal balance barely decreases due to high-interest accrual. The effect of this cap is particularly significant for those with larger loan balances or extended repayment terms, where interest accumulation can be substantial.
The implementation of a 2.5% interest rate cap signifies a robust commitment to making student loan debt more manageable. It empowers borrowers with greater control over their financial futures, enabling them to plan more effectively and reduce the overall cost of their education. This measure is poised to have a profound positive impact on the financial well-being of countless individuals.
Eligibility and Enrollment for the New Programs
Navigating the eligibility requirements and enrollment process for the 2026 student loan repayment plans is essential for borrowers seeking to benefit from the new interest rate cap and other provisions. While specific details are still being finalized, general guidelines are emerging that borrowers should be aware of to prepare for these changes.
The new programs are primarily aimed at federal student loan borrowers. This includes direct subsidized loans, direct unsubsidized loans, direct PLUS loans, and direct consolidation loans. It is crucial for borrowers to confirm the type of their loans to determine their eligibility for the 2.5% interest rate cap and other new benefits. Private student loans are typically not covered by federal programs.
Who Qualifies for the 2.5% Interest Rate Cap?
- Federal Loan Holders: The primary beneficiaries will be individuals with eligible federal student loans.
- Active Repayment: Borrowers in active repayment or those transitioning into repayment in 2026 are expected to qualify.
- Consolidated Loans: Loans that have been consolidated into a Direct Consolidation Loan are likely to be eligible.
The enrollment process is anticipated to be streamlined, with federal loan servicers playing a key role in communicating specific instructions. Borrowers will likely need to ensure their contact information is up-to-date with their loan servicer to receive timely notifications about how to opt into or be automatically enrolled in the new plans. It is advisable to proactively reach out to servicers or visit the official Federal Student Aid website as 2026 approaches.
Furthermore, there may be specific actions required from borrowers, such as updating income information for income-driven repayment (IDR) plans, which are often integrated with interest rate caps to maximize benefits. Staying informed and proactive will be key to successfully transitioning into these new, more favorable repayment structures. The government aims to make this transition as seamless as possible, but individual responsibility in understanding and acting on information remains paramount.
Impact on Income-Driven Repayment (IDR) Plans
The introduction of a 2.5% interest rate cap will significantly enhance the effectiveness of Income-Driven Repayment (IDR) plans. IDR plans are designed to make monthly student loan payments affordable by basing them on a borrower’s income and family size. The new interest rate cap complements these plans by addressing a common frustration: interest accumulation even when payments are made.
Under previous IDR structures, even if a borrower’s payment was set at $0 due to low income, interest could continue to accrue, potentially leading to a larger loan balance over time. This often undermined the very purpose of IDR plans, making long-term debt forgiveness programs less impactful. The 2.5% interest rate cap seeks to rectify this by limiting that accrual.
Synergy Between the Cap and IDR Plans
- Reduced Accrual: For borrowers with low or zero dollar IDR payments, the cap limits the amount of interest that can accrue, preventing balances from growing out of control.
- Faster Path to Forgiveness: By mitigating interest growth, borrowers on IDR plans can see their principal balance reduce more effectively, moving them closer to loan forgiveness at the end of their repayment term.
- Greater Affordability: The combined effect of income-based payments and a capped interest rate creates a more sustainable and less stressful repayment environment.
- Simplified Planning: Borrowers can better predict their total repayment amount and the timeline for loan payoff or forgiveness.
This synergy is particularly beneficial for borrowers in critical early career stages or those experiencing financial hardship, as it provides a stronger safety net. The combination ensures that the IDR promise of affordable payments is not undermined by unchecked interest growth. It reflects a more holistic approach to student loan management, recognizing the varying financial capacities of borrowers throughout their lives.
Borrowers currently on or considering IDR plans should pay close attention to how these changes will be integrated. The reforms are expected to make IDR plans a more powerful tool for managing student debt, potentially leading to earlier debt freedom and greater financial stability for millions.
Comparing 2026 Plans to Previous Repayment Options
To fully appreciate the significance of the 2026 student loan repayment plans, it’s helpful to compare them with previous repayment options. Historically, the federal student loan system offered a variety of plans, including Standard, Graduated, Extended, and several Income-Driven Repayment (IDR) options. While these plans aimed to provide flexibility, they often fell short in addressing the core issue of rapidly accumulating interest.
One of the primary differences lies in the direct intervention on interest rates. Before 2026, interest rates were primarily determined by market forces and fixed at loan origination, with no universal cap. This meant borrowers were largely at the mercy of economic conditions and the initial terms of their loans, which could lead to substantial and often unexpected increases in the total cost of their education.
Key Differences and Advantages of 2026 Plans
- Interest Rate Control: The 2.5% interest rate cap is a fundamental departure, directly limiting the cost of borrowing, which was absent in prior general federal programs.
- Enhanced IDR Benefits: While IDR plans existed, the cap strengthens their protective measures, ensuring that interest does not negate the benefits of lower monthly payments.
- Simplified Choices: The new framework aims for greater clarity and potentially fewer, more effective repayment options, reducing borrower confusion.
- Long-Term Savings: For many, the cap will result in significant savings over the life of the loan, something less guaranteed under previous plans.
Previous plans, while offering some relief, did not provide the same level of interest rate predictability and protection. For instance, the Revised Pay As You Earn (REPAYE) or Pay As You Earn (PAYE) plans offered lower monthly payments based on income, but interest could still accrue, particularly if payments were less than the accruing interest. This often led to negative amortization, where the loan balance grew despite payments.
The 2026 plans represent a more borrower-centric approach, prioritizing the reduction of overall debt burden and providing a clearer path to financial freedom. This shift is expected to reduce default rates and improve the financial health of former students, allowing them to participate more robustly in the economy. It marks a significant evolution in federal student aid policy, moving towards more sustainable and equitable solutions.
Anticipated Benefits and Potential Challenges
The 2026 student loan repayment plans, with their groundbreaking 2.5% interest rate cap, are poised to deliver a multitude of benefits to borrowers across the United States. However, like any large-scale federal initiative, they may also present certain challenges during implementation and adjustment. Understanding both sides of the coin is crucial for a balanced perspective.
On the benefit side, the most obvious advantage is the significant reduction in the total cost of student loans for many borrowers. The interest rate cap directly lowers the amount of interest paid over the life of the loan, translating into substantial savings. This not only frees up disposable income but also accelerates the path to debt freedom, allowing individuals to pursue other financial goals like homeownership or retirement savings.
Expected Benefits
- Reduced Financial Stress: Lower and more predictable payments alleviate anxiety associated with student debt.
- Increased Disposable Income: Borrowers will have more funds available for other expenses, stimulating local economies.
- Improved Credit Scores: More manageable payments can lead to fewer delinquencies and defaults, positively impacting credit.
- Economic Stimulus: The broader economic impact is expected to be positive, as reduced debt burdens encourage spending and investment.
Despite these promising benefits, potential challenges could arise. The sheer scale of updating and implementing these new programs across all federal loan servicers could lead to initial administrative hurdles. Borrowers might experience delays or confusion during the transition period, emphasizing the need for clear communication from federal agencies and loan servicers. Additionally, ensuring all eligible borrowers are aware of and successfully enroll in the new plans will be a significant undertaking.
Another potential challenge could be the fiscal impact on the federal budget, though the long-term economic benefits of a healthier, less indebted populace are often argued to outweigh these costs. Borrowers should remain vigilant, stay informed, and actively engage with their loan servicers to navigate any potential issues smoothly. Overall, the benefits are expected to far outweigh the challenges, ushering in a new era of student loan management.
Preparing for the 2026 Student Loan Changes
As the implementation of the 2026 student loan repayment plans draws nearer, proactive preparation is key for borrowers to maximize the benefits, particularly the 2.5% interest rate cap. Understanding what steps to take now can ensure a smooth transition and immediate access to the new, more favorable terms.
The first and most crucial step is to gather all relevant information about your current federal student loans. This includes knowing your loan types, current interest rates, principal balances, and who your loan servicer is. This information will be vital for assessing how the new programs will specifically impact your financial situation and for communicating effectively with your servicer.
Essential Steps for Borrowers
- Verify Loan Types: Confirm that your loans are federal and eligible for the new programs.
- Update Contact Information: Ensure your loan servicer has your current mailing address, email, and phone number.
- Monitor Official Announcements: Regularly check the Federal Student Aid website and communications from your servicer for updates.
- Understand Your Options: Familiarize yourself with the details of the 2.5% interest rate cap and how it integrates with IDR plans.
- Consult a Financial Advisor: For complex situations, consider seeking advice from a financial expert specializing in student loans.
It is also advisable to review your current repayment plan. If you are not already on an Income-Driven Repayment (IDR) plan, understanding how the new interest rate cap will interact with IDR might make switching to one more appealing. The goal is to align your repayment strategy with the most beneficial aspects of the 2026 reforms.
Do not wait until the last minute to act. Staying informed, organized, and proactive will empower you to take full advantage of the improved student loan landscape. These changes represent a significant opportunity for financial relief, and careful preparation will ensure you are well-positioned to benefit from them.
| Key Aspect | Brief Description |
|---|---|
| Interest Rate Cap | Federal student loan interest rates capped at 2.5%, reducing overall repayment costs. |
| Eligibility | Applies to most federal student loans, including existing and new loans from 2026. |
| IDR Integration | Enhances Income-Driven Repayment plans by limiting interest accrual, aiding forgiveness. |
| Borrower Preparation | Verify loan types, update contact info, and monitor official announcements for smooth transition. |
Frequently Asked Questions About 2026 Student Loan Plans
The primary benefit is the introduction of a 2.5% interest rate cap on eligible federal student loans. This cap significantly reduces the total amount of interest borrowers will pay over the life of their loans, making repayment more affordable and predictable.
The 2.5% interest rate cap and other new federal programs are generally applicable to eligible federal student loans. Private student loans are typically not covered by these federal initiatives, so borrowers should verify their loan types.
The interest rate cap will greatly enhance IDR plans by limiting interest accrual, even if your monthly payment is low or $0. This prevents your loan balance from growing excessively, potentially leading to faster progress towards loan forgiveness.
You should verify your federal loan types, update your contact information with your loan servicer, and closely monitor official announcements from Federal Student Aid. Understanding your current loans will help you navigate the transition effectively.
Yes, the 2.5% interest rate cap is expected to apply to both new federal student loans originated in 2026 and existing eligible federal student loans, ensuring widespread relief for current and future borrowers.
Conclusion
The advent of the 2026 student loan repayment plans, particularly with the introduction of a 2.5% interest rate cap, marks a pivotal moment for millions of Americans grappling with educational debt. These new federal programs are designed to offer substantial relief, transforming the landscape of student finance from one of burden to one of greater manageability and predictability. By understanding the eligibility criteria, the mechanics of the interest rate cap, and its synergy with income-driven repayment plans, borrowers can proactively position themselves to benefit from these significant reforms. The path to financial freedom post-graduation is becoming clearer and more attainable, fostering a more secure economic future for individuals and the nation as a whole.
